
Table of Contents
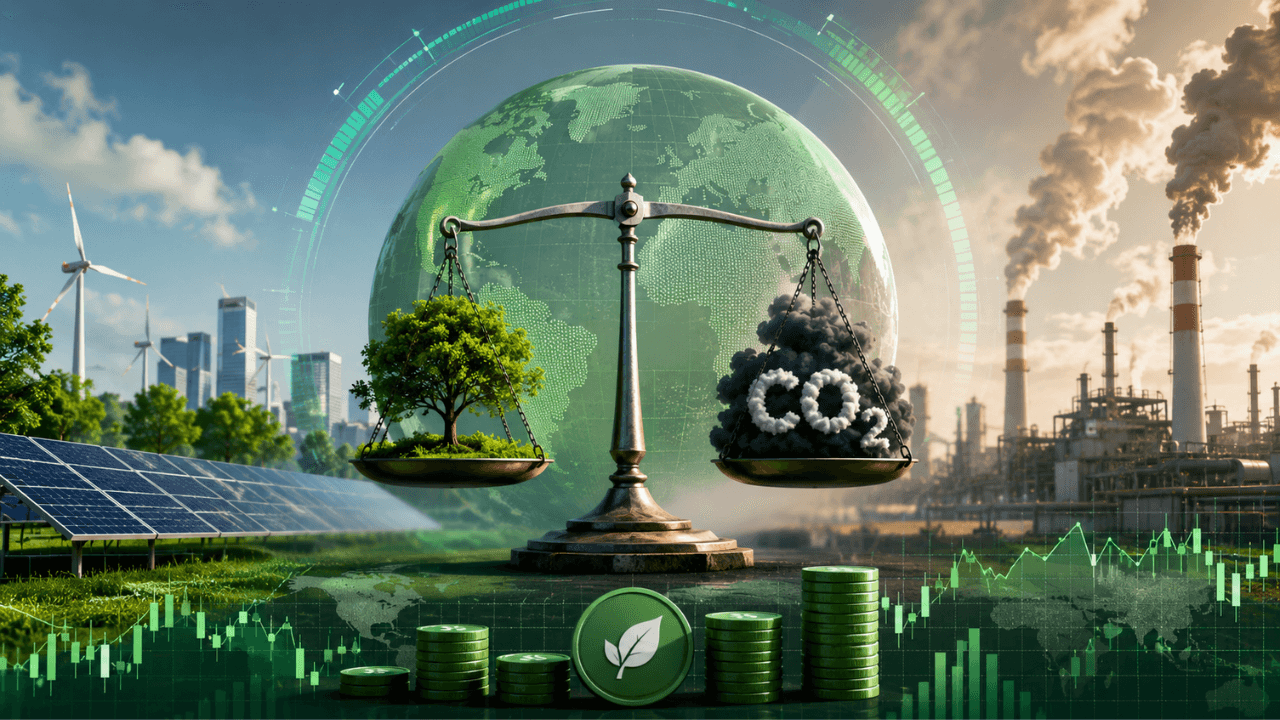
The implementation of environmental border mechanisms has created significant dialogue across global supply chains, making carbon pricing relief for Indian exporters to UK markets a critical topic for international trade policy. As nations tighten their ecological regulations to combat climate change, businesses operating internationally must adapt to complex cross-border levies. This comprehensive overview examines how recent policy adjustments and diplomatic negotiations aim to shield developing manufacturing sectors from disproportionate financial penalties while fostering sustainable industrial practices.
Understanding Carbon Pricing Relief for Indian Exporters to UK
International commerce faces a paradigm shift as environmental accountability becomes a core component of customs regulations. For enterprises based in South Asia, adjusting to shifting British environmental policies dictates future market competitiveness. The dialogue surrounding carbon pricing relief for Indian exporters to UK destinations focuses heavily on mitigating the financial impact of the Carbon Border Adjustment Mechanism (CBAM) and similar regulatory frameworks.

Historically, heavy industries such as steel, aluminum, and cement have contributed significantly to export volumes. However, differing domestic emission standards versus destination-market thresholds create commercial friction. Policy discussions aim to establish equitable frameworks that recognize domestic green initiatives already implemented by developing economies.
The Evolution of Cross-Border Environmental Levies
Environmental tariffs are designed to prevent carbon leakage—a scenario where companies relocate production to regions with laxer emission controls. To counter this, importing nations introduce border adjustments. Key aspects of this regulatory evolution include:
- Phased implementation timelines allowing businesses to adapt reporting protocols.
- Recognition of domestic carbon taxes paid in the country of origin.
- Technical assistance and capacity-building programs for small and medium enterprises (SMEs).
The Mechanics of CBAM and Trade Impacts
The operational framework of border carbon adjustments requires meticulous tracking of greenhouse gas emissions embedded in manufactured goods. Exporters must calculate both direct emissions from production processes and indirect emissions from electricity consumption.

Without adequate exemptions or offset recognitions, these regulatory costs could price competitive products out of Western markets. Consequently, bilateral discussions between trade authorities emphasize mutual recognition of green taxation structures.
Comparative Impact on Key Sectors
Different industrial sectors experience varying degrees of regulatory exposure. The table below outlines the projected vulnerability and mitigation measures for primary export categories:
| Sector | Primary Emission Source | Vulnerability Level | Proposed Mitigation |
|---|---|---|---|
| Steel & Iron | Coal-fired blast furnaces | High | Transition to green hydrogen and electric arc furnaces |
| Aluminum | Electricity consumption | High | Integration of renewable energy power purchase agreements |
| Chemicals | Process emissions & heating | Medium | Energy efficiency upgrades and waste heat recovery |
Strategic Advantages for Indian Industries
Adapting to stringent environmental mandates presents both operational challenges and strategic opportunities. Enterprises that proactively decarbonize their supply chains position themselves favorably in global procurement networks.

Furthermore, securing diplomatic relief or transitional allowances gives regional manufacturers a temporary competitive edge over peers who delay sustainable transformations. Investment in green technologies ultimately lowers long-term operational expenditures while safeguarding market share.
Navigating Future Compliance and Challenges
Despite positive diplomatic engagement, compliance hurdles remain complex. Accurate carbon accounting demands robust data infrastructure, which many mid-sized enterprises currently lack. Regulatory bodies continue to emphasize capacity building to ensure seamless reporting integration.

Industry leaders recommend investing in digital auditing tools and collaborating closely with trade associations to stay informed about evolving policy benchmarks and bilateral agreements.
Conclusion
The ongoing discussions regarding carbon pricing relief for Indian exporters to UK markets underscore the delicate balance between environmental protection and international trade equity. While regulatory hurdles like CBAM present formidable compliance tasks, they also accelerate the necessary transition toward sustainable industrial practices. By embracing green technologies and proactive reporting standards, businesses can secure their position in the global economy of tomorrow.