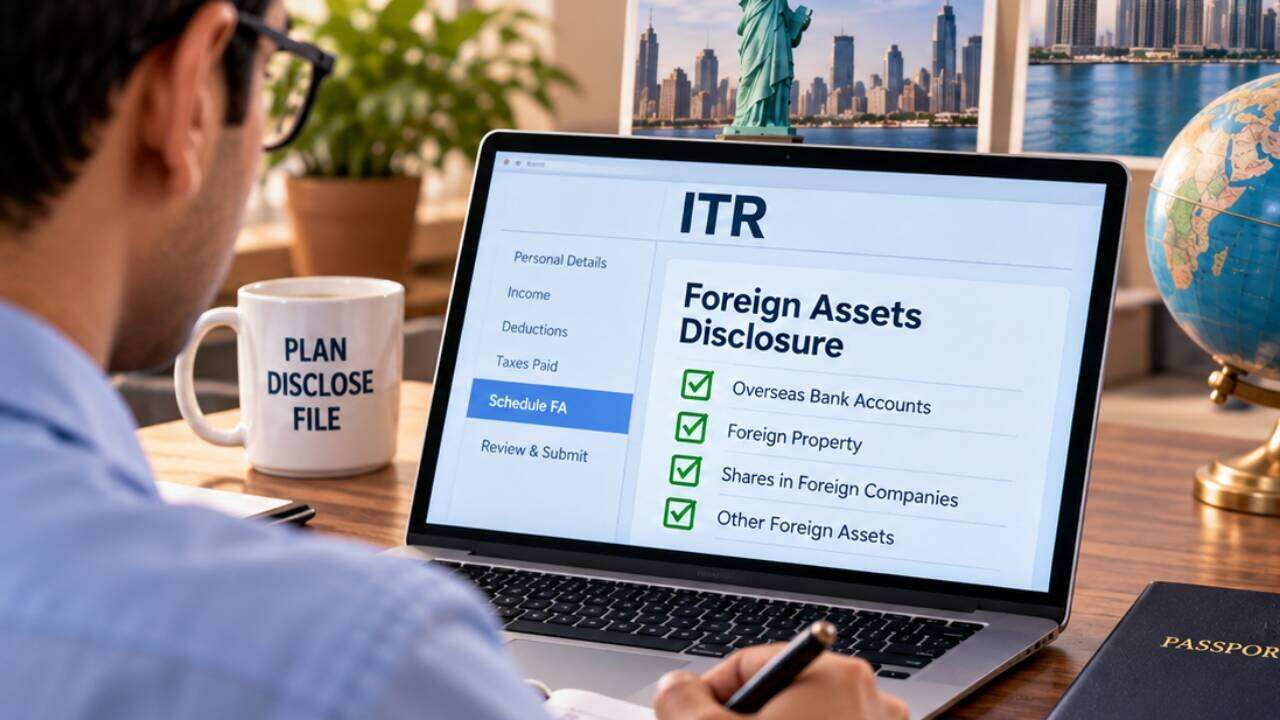

Navigating international taxation can be a daunting experience, particularly for everyday individuals who may inadvertently hold minor overseas assets without proper documentation. To address these compliance challenges, the government introduced a progressive initiative. The Foreign Assets of Small Taxpayers – Disclosure Scheme, commonly referred to as FAST-DS 2026, provides a vital pathway for ordinary residents to regularize overlooked holdings without facing severe penal consequences.
| Feature | Details |
|---|---|
| Announcement | Union Budget 2026 |
| Notification Date | 14 August 2026 |
| Effective Date | 16 August 2026 |
| Target Audience | Small Taxpayers |
Table of Contents
- Introduction to FAST-DS
- Understanding the Rules and Eligibility
- Filing Forms and Compliance Procedures
- Key Benefits for Small Taxpayers
- Conclusion
Introduction to FAST-DS 2026
Originally proposed during the Union Budget announcements, the framework has now transitioned from policy proposal to active regulation. Following the formal official notification released on August 14, 2026, and its subsequent implementation on August 16, 2026, taxpayers finally have the operational clarity required to declare undisclosed foreign assets legally and transparently.
Proper documentation is crucial for international asset compliance.
Understanding the Rules and Eligibility
The core objective of this mechanism is to offer administrative relief. Historically, minor oversights regarding foreign bank accounts, overseas insurance policies, or small equity holdings could trigger exhaustive scrutiny under stringent anti-black money legislation. The latest provisions create a specialized window for correction.
Who Qualifies as a Small Taxpayer?
While larger corporations and high-net-worth individuals are generally subject to rigorous compliance frameworks, this initiative focuses specifically on lower-tier asset holders. Eligibility criteria revolve around the total valuation threshold of the unlisted overseas holdings.
- Minor foreign bank accounts with minimal balances
- Undeclared overseas employee stock options (ESOPs)
- Small immovable properties inherited abroad below specific valuation caps
Filing Forms and Compliance Procedures
Complying with the new framework requires utilizing newly designated administrative forms. Tax authorities have streamlined the declaration process to minimize bureaucratic delays.
Taxpayers must carefully verify all details before final submission.
Step-by-Step Submission Process
- Gather all historical documentation regarding the foreign asset.
- Access the official taxation portal to download the newly prescribed disclosure documents.
- Fill in asset valuations accurately as of the specified baseline date.
- Pay any applicable processing fees or settlement amounts.
- Submit the documentation electronically and retain the confirmation receipt.
Key Benefits for Small Taxpayers
Participating in the initiative grants several legal immunities and financial advantages. Most importantly, compliant individuals receive immunity from prosecution under specific aggressive anti-evasion statutes, provided all disclosures are truthful and complete.
- Peace of mind regarding historical non-compliance
- Reduction in potential financial penalties
- Cleaner financial profiles for future wealth management
Conclusion
The implementation of FAST-DS marks a constructive shift toward cooperative tax administration. By balancing strict regulatory oversight with a pragmatic amnesty route, the framework encourages voluntary compliance. Individuals with qualifying international holdings should evaluate their portfolios and consult qualified professionals to utilize this timely administrative window effectively.