
Table of Contents
Introduction to the ITAT Delhi Ruling
Navigating the complexities of Indian tax laws can often lead to intense litigation between taxpayers and revenue authorities. In a recent landmark judgment, the Income Tax Appellate Tribunal (ITAT) in New Delhi provided significant relief to a taxpayer facing a hefty penalty. The core of the matter involved a minor child earning substantial interest income, which subsequently led to a dispute over under-reporting and tax rates. Understanding tax disputes is crucial for high-net-worth individuals who must manage intricate family portfolios.

Background of the Tax Dispute
The legal battle originated in New Delhi when a taxpayer filed his income tax return on November 4, 2022, declaring a substantial total income of Rs 8.43 crore. Months later, on March 22, 2025, the Income Tax Assessing Officer (AO) at Jhandewalan decided to reopen the case. The scrutiny primarily focused on how specific financial streams within the family were reported, particularly concerning investment returns generated by a minor dependent.
The Scrutiny and Assessment
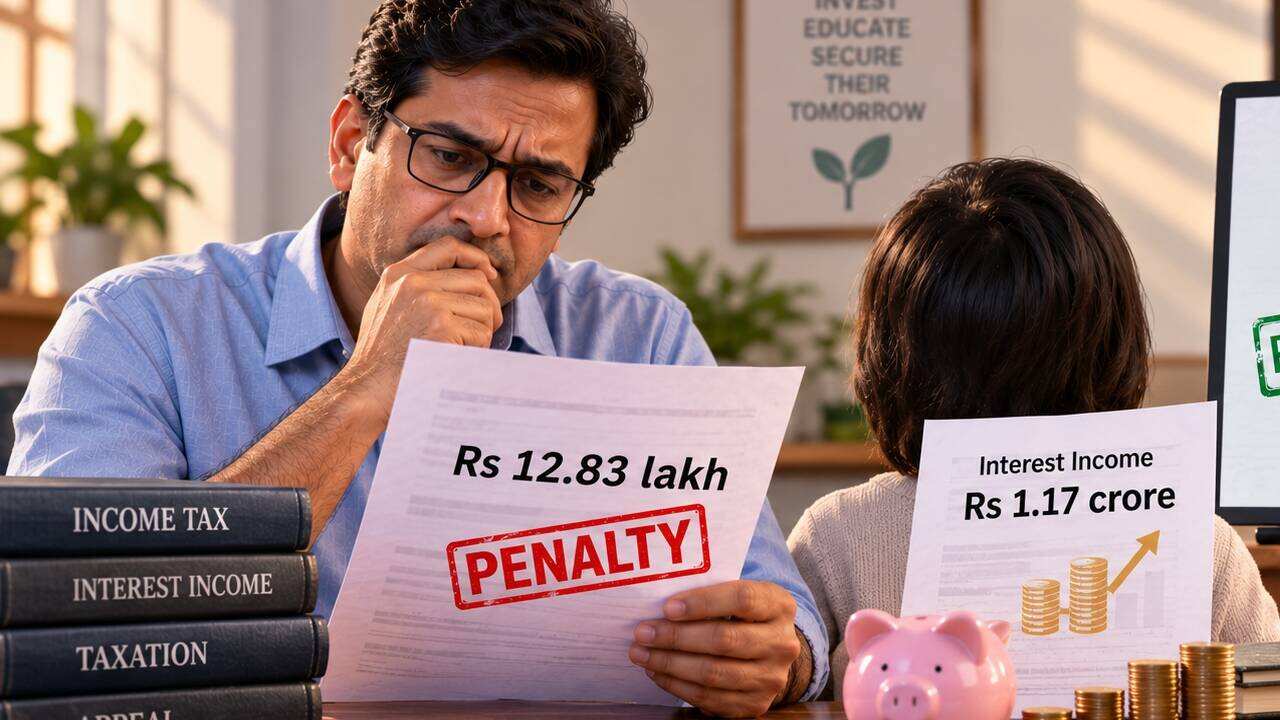
During the reassessment phase, tax authorities flagged discrepancies regarding the classification of income sources. The department argued that certain disclosures fell short of statutory requirements, prompting them to levy a penalty of Rs 12.83 lakh under provisions relating to under-reporting of income. Taxpayers often find themselves grappling with such income tax assessment tips to safeguard against unexpected penalties.
Understanding Minor Interest Income and Clubbing Rules
Under the Indian Income Tax Act, specific provisions govern the income of minor children. Generally, any income accruing to a minor must be clubbed with the income of that parent whose total income is higher. In this particular case, the minor child had amassed a notable Rs 1.17 crore in interest income. While the clubbing mechanism itself was not disputed, the legal interpretation of how this income was categorized sparked a fierce debate.
- Minor income is typically added to the parent’s taxable base.
- Interest from fixed deposits and savings accounts forms a major part of this pool.
- Disclosures must explicitly separate these streams to avoid administrative confusion.
Why ITAT Delhi Cancelled the Penalty
Upon appeal, the ITAT Delhi closely examined the rationale behind the Rs 12.83 lakh penalty imposed by the Assessing Officer. The tribunal observed that a mere difference in opinion or a dispute over tax rates and legal interpretations cannot automatically be equated with the “under-reporting” or “misreporting” of income.
| Case Parameter | Details |
|---|---|
| Taxpayer Income | Rs 8.43 crore |
| Minor Interest Income | Rs 1.17 crore |
| Penalty Imposed | Rs 12.83 lakh |
| ITAT Verdict | Penalty Cancelled |
Distinguishing Tax Rate Disputes from Concealment
The tribunal highlighted a fundamental principle of taxation law: honest disclosure of facts, even if accompanied by a debatable legal stance on tax rates, does not attract penalty provisions. Because the taxpayer had fully disclosed the financial particulars of the minor’s earnings in the financial records, the allegation of hiding income crumbled. You can read more about legal precedents on tax penalties to understand how tribunals protect compliant filers.
Broader Implications for Taxpayers
This ruling serves as a vital precedent for assesses across India who face aggressive penalty proceedings due to classification disagreements with assessing officers. It reinforces the notion that transparency in filing returns protects individuals from punitive financial measures, even when high-value transactions or large sums are involved.
Conclusion
The ITAT Delhi decision underscores the importance of transparent financial disclosures while offering protective clarity against arbitrary penalty impositions. By establishing that tax rate disputes do not constitute under-reporting, the tribunal has provided welcome reassurance to families managing complex investment portfolios involving minors.