
Table of Contents
Introduction
Property papers lost by financial institutions pose a severe challenge to property owners, often leaving them in prolonged legal limbo. A recent landmark judicial decision by the Bombay High Court has addressed this critical issue head-on. When a borrower fully discharges their financial obligations, returning the original title deeds is a mandatory duty. This comprehensive article explores a case where a commercial bank misplaced vital documents years after a loan was settled, resulting in a substantial daily financial penalty.
The Legal Battle and Court Ruling
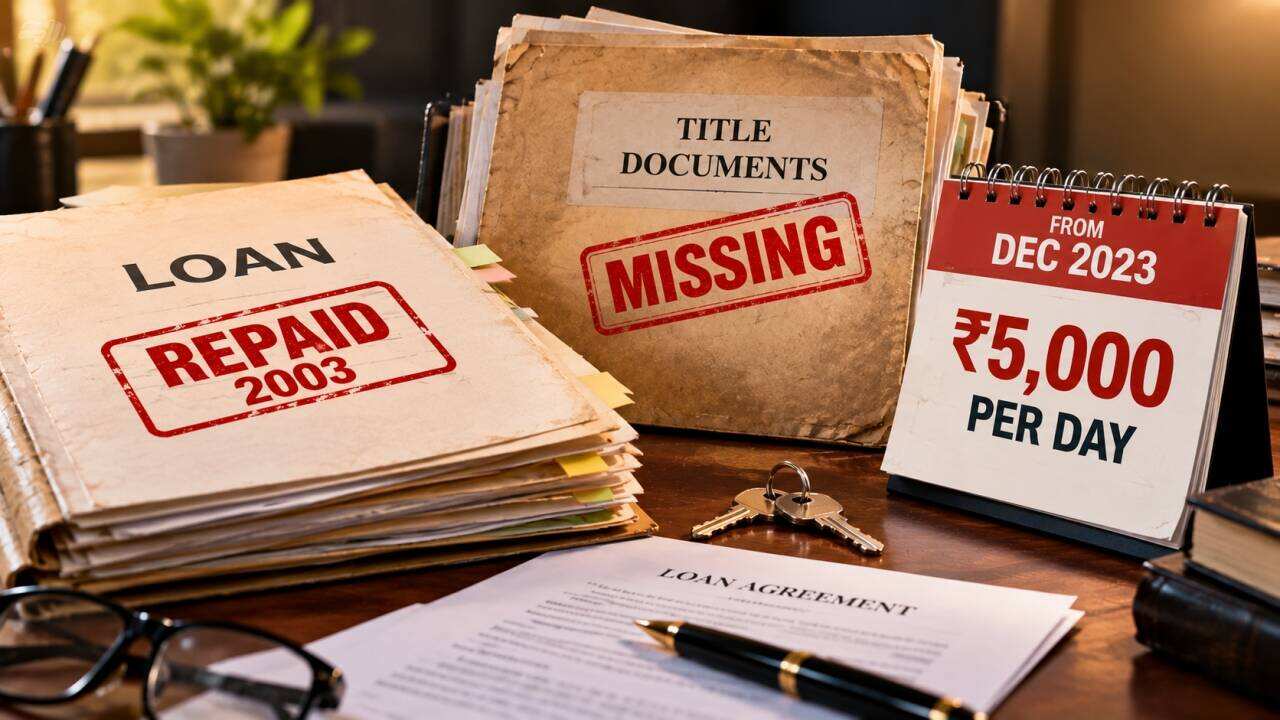
The core of the dispute centers on a business loan that was fully paid off in 2003. Despite the clearance of all dues, the lending institution failed to return the original deeds for two distinct properties pledged as collateral. Years later, when the firm demanded the documents, the institution admitted it could not trace them.
Faced with administrative apathy, the affected party sought judicial intervention. The court did not look kindly upon the institution’s negligence. Consequently, the judiciary ordered a unique penalty structure to compel action:
- Daily compensation payout set at Rs 5,000.
- Penalty accrual starting from December 2023.
- Mandatory reconstruction of lost title records.
Banking Responsibility and Lost Property Papers
During the proceedings, the defense attempted to shift partial blame onto the borrower. The institution argued that the firm did not immediately request the return of the deeds right after the final payment in 2003. However, judicial authorities rejected this argument, emphasizing that custodial responsibility remains with the institution regardless of when the demand is officially lodged.

Misplacing collateral documents creates massive hurdles for citizens. Without original deeds, property owners face immense difficulties during future sales, transfers, or applications for fresh credit lines. Reconstructing titles requires navigating complex bureaucratic channels, public notices, and legal affidavits.
Broader Implications for Borrowers
This ruling serves as a vital reminder to the financial sector regarding accountability. Key takeaways include:
- Institutions must maintain robust digital and physical archives.
- Delays in returning collateral can invite strict monetary penalties.
- Borrowers possess legal remedies against custodial negligence.
Financial experts advise all borrowers to secure a formal ‘No Dues Certificate’ and collect all original collateral immediately upon loan closure. Proactive tracking minimizes future disputes and ensures absolute legal clarity over real estate assets.
Conclusion
The ruling involving property papers lost by the bank highlights the judiciary’s firm stance on consumer protection and institutional accountability. By imposing a stringent daily penalty, the court has set a powerful precedent ensuring financial entities treat collateral stewardship with the utmost seriousness.