
Table of Contents
Introduction to RBI Tech Concentration Risks
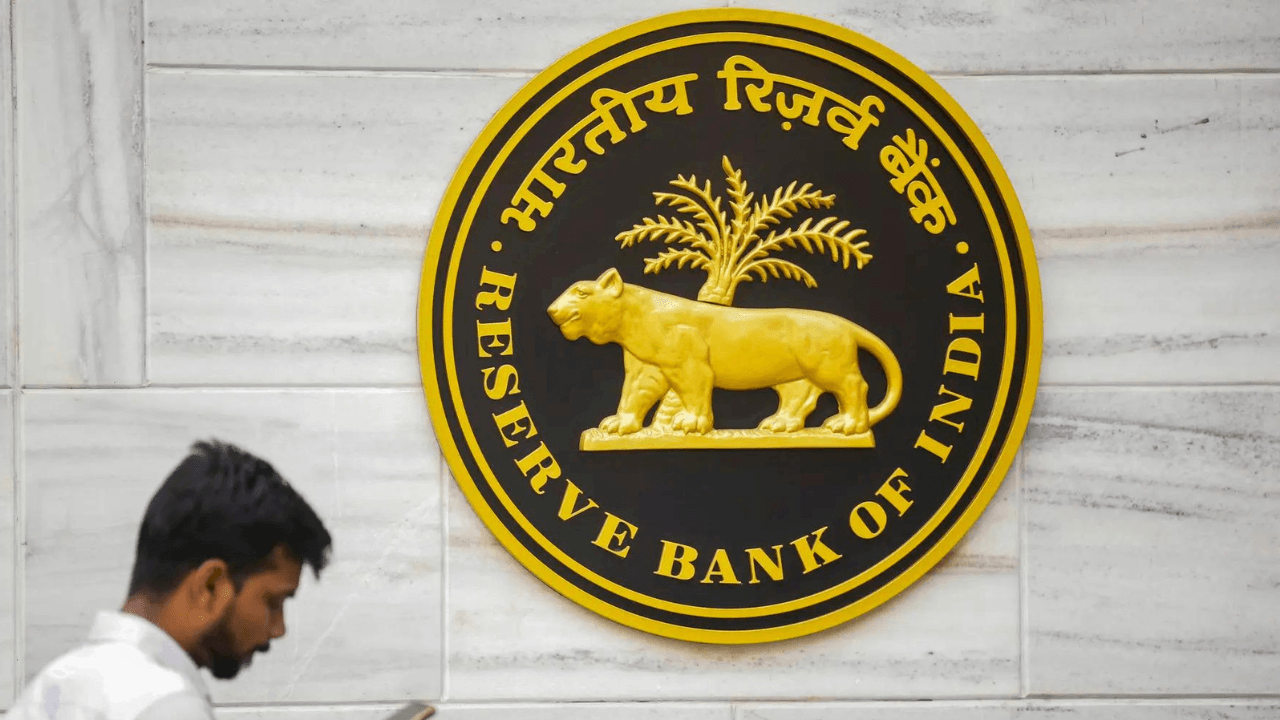
RBI tech concentration risks have emerged as a critical talking point for financial regulators across the globe, and India is no exception. As banks and financial institutions increasingly rely on a handful of third-party technology providers for their core operations, cloud computing, and payment gateways, the vulnerability of the entire financial ecosystem multiplies. In recent times, the Reserve Bank of India has issued stern warnings regarding this heavy reliance, highlighting how a single point of failure in technological infrastructure could bring down critical financial services and trigger widespread market disruptions.
The modern digital banking landscape offers unprecedented convenience, speed, and efficiency to millions of customers. However, beneath this polished digital facade lies a complex web of shared dependencies. When multiple financial entities depend on the exact same cloud service providers, software vendors, or payment processors, systemic risk is no longer a distant theoretical threat. It is an active hazard that requires urgent strategic intervention, robust risk management frameworks, and proactive regulatory oversight.
Understanding Technology Concentration in Banking
Technology concentration occurs when a significant portion of the financial sector relies on a very small number of technology vendors or service providers. This phenomenon is particularly prevalent in areas such as cloud infrastructure, data storage, cybersecurity solutions, and core banking software. While partnering with established tech giants often brings cost efficiencies and advanced capabilities, it simultaneously concentrates risk in unprecedented ways.
- Cloud Infrastructure Dependency: A majority of financial institutions outsource their heavy data workloads to just a few hyperscale cloud providers.
- Payment Gateways: High reliance on dominant payment processors creates systemic vulnerability if transactions halt suddenly.
- Core Banking Software: Limited vendors providing core banking solutions mean software bugs affect multiple institutions simultaneously.
Understanding these dependencies requires looking at how traditional banking models have evolved. Decades ago, banks maintained localized servers and isolated technological frameworks. Today, hyper-connectivity is the norm. While this enables seamless cross-border transactions and instant digital payments, it exposes the financial architecture to cascading failures.
Potential Disruptions and Systemic Vulnerabilities
When technology fails in a concentrated environment, the consequences extend far beyond a single institution. A localized outage at a major cloud provider can instantly paralyze multiple banks, leaving customers unable to access funds, execute trades, or clear checks. The Reserve Bank of India has repeatedly emphasized that such disruptions pose severe threats to financial stability and consumer trust.
Furthermore, cybersecurity risks amplify these concerns. A sophisticated cyber attack targeting a widely used third-party vendor could compromise the data and operations of numerous financial institutions concurrently. This multiplier effect makes third-party tech vendors systemic nodes within the financial network, demanding the same level of regulatory scrutiny traditionally reserved for large commercial banks.
Regulatory Measures and Mitigation Strategies
To counteract these escalating threats, financial regulators are formulating stricter guidelines for outsourcing and technology risk management. Institutions are being urged to diversify their vendor base, adopt multi-cloud strategies where feasible, and maintain comprehensive exit plans in case a technology partner fails or breaches compliance.
Additionally, stress testing is becoming a mandatory practice. Banks must simulate severe technology outages to evaluate their operational resilience and ensure business continuity plans function effectively under pressure. Cooperation between financial institutions and technology providers is paramount to establishing transparency, accountability, and robust security standards across the supply chain.
Conclusion
In summary, the warnings issued by the central bank regarding RBI tech concentration risks serve as a timely wake-up call for the financial sector. While technological innovation drives growth and accessibility, it must be balanced with rigorous risk management and operational resilience. By diversifying technology partnerships, investing in robust cybersecurity, and adhering to strict regulatory frameworks, the financial ecosystem can safeguard itself against catastrophic disruptions and ensure sustained stability for the future.