
Table of Contents
Introduction
When the taxman seized gold, diamonds, and silver from a taxpayer, it sparked a multi-year legal battle that ultimately highlighted the importance of proper documentation in India’s complex tax landscape. Navigating income tax scrutiny can be an overwhelming experience, especially when high-value precious metals and jewelry are involved. This comprehensive case study examines how a routine tax return filing escalated into a major investigation and how the Income Tax Appellate Tribunal (ITAT) ultimately ruled in favor of the taxpayer, deleting substantial tax additions.

Background of the Tax Dispute
The controversy originated when an individual taxpayer submitted her income tax return (ITR) for the financial year. Declaring a modest income of Rs 1.34 lakh, she believed her financial obligations were properly settled. However, tax authorities operate on broader data networks and intelligence gathering mechanisms that often track high-value transactions well before a return is formally evaluated.
Approximately one year prior to her filing date, the Income Tax Department launched a widespread search and seizure operation at the corporate offices of an enterprise. During this corporate raid, investigators uncovered transactional records, financial trails, and digital data pointing toward various individuals, ultimately drawing the attention of enforcement officers to the taxpayer in question.
Initial Trigger Points
Financial investigations typically begin with specific data anomalies. In this case, corporate records suggested connections between the company and the taxpayer, prompting authorities to dig deeper into her personal assets, bank accounts, and residential premises. For more insights on handling financial audits, read our guide on navigating corporate tax audits.
Search and Seizure Operations
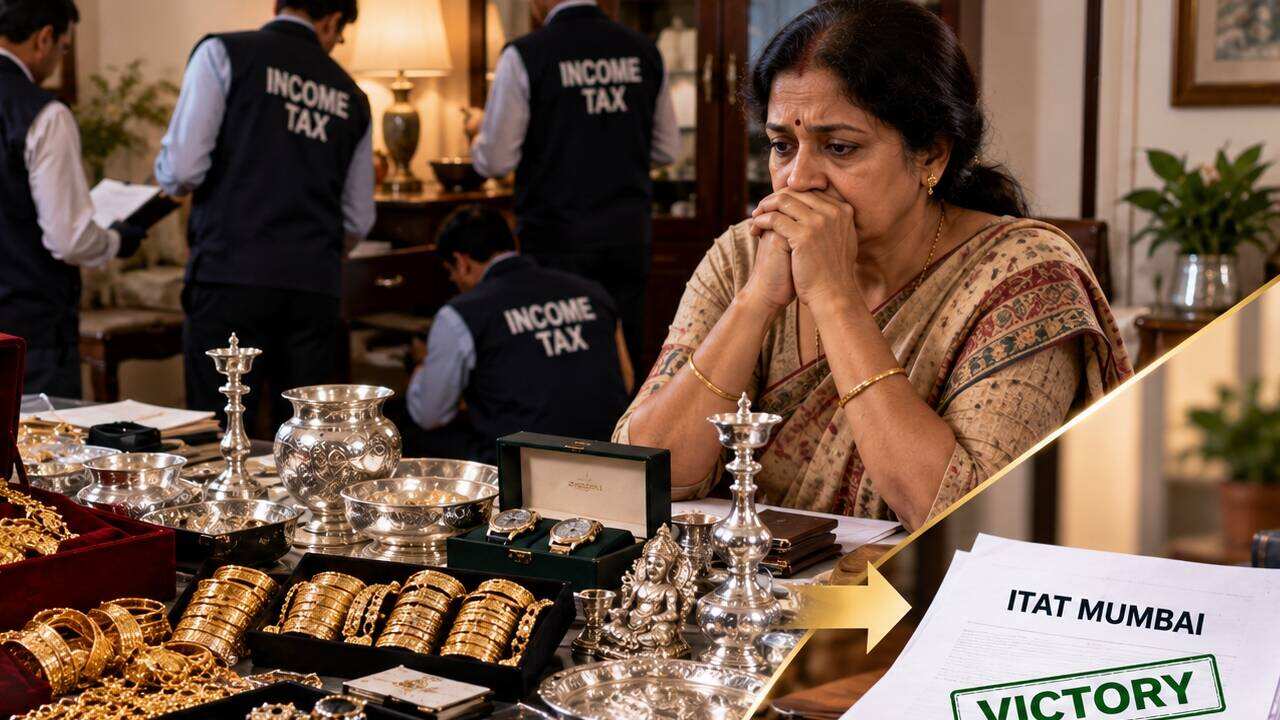
Acting on the intelligence gathered from the corporate offices, tax authorities extended their investigation to the taxpayer’s personal spaces. Officers conducted searches at her residential premises and inspected designated bank lockers. During these operations, enforcement teams discovered and subsequently confiscated significant quantities of valuables.
- Gold ornaments and jewelry
- Diamond-studded luxury pieces
- Silver utensils and bullion items
- Physical cash and related financial documents
Following the confiscation, tax officials initiated assessment proceedings, arguing that the origin of these valuable assets could not be fully explained by the taxpayer’s declared annual income of Rs 1.34 lakh. Consequently, authorities added substantial sums to her taxable income, leading to a major financial dispute.
The Legal Battle at ITAT
Displeased with the assessing officer’s decision, the taxpayer challenged the additions through the appellate hierarchy, eventually reaching the Income Tax Appellate Tribunal (ITAT). The core of her defense relied on establishing the legitimate family heritage, past disclosures, and traditional acquisitions of the precious items.
| Stage of Dispute | Declared Income / Amount | Action Taken |
|---|---|---|
| Initial ITR Filing | Rs 1.34 Lakh | Filed regular return for the assessment year |
| Tax Assessment | Disputed Additions (Rs 11.23 Lakh+) | Taxman seized gold and added value to income |
| ITAT Verdict | Relief Granted | Tribunal deleted the contested additions |
The tribunal carefully reviewed the evidence presented by both sides. It evaluated the customary ownership of jewelry within Indian households, noting that traditional holdings passed down through generations do not always carry modern purchase receipts. Ultimately, the ITAT ruled that the tax department could not sustain the additions merely on assumptions without concrete proof of undisclosed income.
Tribunal Findings
The ITAT emphasized that possession of gold and jewelry, within reasonable limits expected of a family’s social standing and cultural traditions, does not automatically constitute unexplained income. Discover more about property rights and asset declarations in our legal rights during tax investigations resource.
Key Takeaways for Taxpayers
This landmark case offers essential lessons for individuals seeking to protect their assets from unwarranted tax disputes. Proper record-keeping remains the single most effective defense against aggressive tax enforcement actions.
- Maintain clear records of inherited jewelry and family gifts.
- File accurate wealth and income declarations where applicable.
- Consult qualified tax professionals immediately upon receiving a notice.
- Understand your legal rights during search and seizure operations.
Conclusion
The ITAT ruling provides substantial relief to taxpayers facing aggressive asset additions during scrutiny assessments. While the spectacle of the taxman seized gold and other valuables creates immense stress, the judiciary continues to protect legitimate holdings supported by reasonable explanations and cultural context. Taxpayers must remain vigilant, maintain transparent records, and utilize appellate mechanisms to safeguard their financial interests.